Turnall Holdings Limited has reported a total comprehensive loss of US$665,856 for the half-year ended 30 June 2026, compared to a loss of US$244,884 in the prior year, despite a 15% growth in revenue to US$5.81 million.
The Group’s abridged unaudited consolidated financial results, approved by the Board on 8 September 2026, show that the increased loss was driven by lower gross margins, higher finance costs and a deferred tax charge.
Turnall said Zimbabwe’s macroeconomic environment remained relatively stable during the first half, characterised by low inflation, stable exchange rates and improved foreign currency inflows, although liquidity challenges persisted, borrowing costs remained high and consumer purchasing power was constrained. Global supply-chain disruptions linked to the Middle East conflict also pushed energy prices higher.
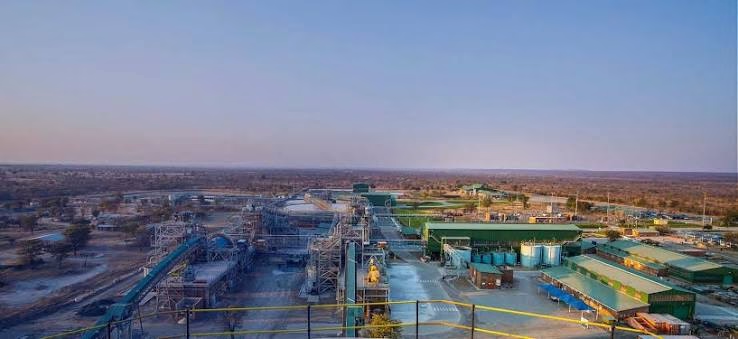
Revenue growth was underpinned by a 33% increase in sales volumes to 16,807 tonnes from 12,674 tonnes in 2025, while production volumes grew 32% to 21,420 tonnes from 16,236 tonnes following the commissioning of the new fibre-cement manufacturing plant in Harare in March 2026.
Despite the strong turnover, gross margin declined to 20% from 25% in the comparative period due to pricing pressures in a competitive market, higher production costs incurred during commissioning of the new plant, and a change in sales mix towards concrete products. Management said efforts are underway to optimise the plant’s performance, with costs expected to moderate as efficiencies improve.
Operating expenses declined by 4% despite the 15% increase in turnover, reflecting effective cost-containment measures. Finance costs, however, increased by 109% to US$139,800, as borrowing costs previously capitalised during construction are now being expensed following commissioning.
Operationally, the commissioning of the Harare fibre-cement plant marks a transformational milestone, significantly enhancing manufacturing capability, product quality and operational flexibility. company’s focus during the period was on stabilising production and optimising machine performance.
On strategic investments, the company said it remains committed to long-term value creation. Plans are underway to upgrade the Bulawayo sheeting plant to enable it to use synthetic fibres for exports. The Group also invested US$239,938 in a joint venture as part of its diversification strategy.
The company maintained a stable financial position with total assets of US$32.37 million and total equity of US$24.23 million. Operating cash flows remained positive at US$285,451, providing support for ongoing operations. Borrowings are largely shareholder loans that are Sharia-compliant and attract a 10% profit share, used mainly to finance the new plant.
The company said it is confident that it is well-resourced to meet its obligations over the next 12 months, supported by the successful plant commissioning, enhanced production capacity, anticipated revenue growth and ongoing cost-containment measures.
The company is confident that investments made in recent years have laid a strong foundation for sustainable growth and improved profitability in the medium term, with the new plant expected to achieve higher utilisation in the second half of the year.
No dividend was declared for the period.